
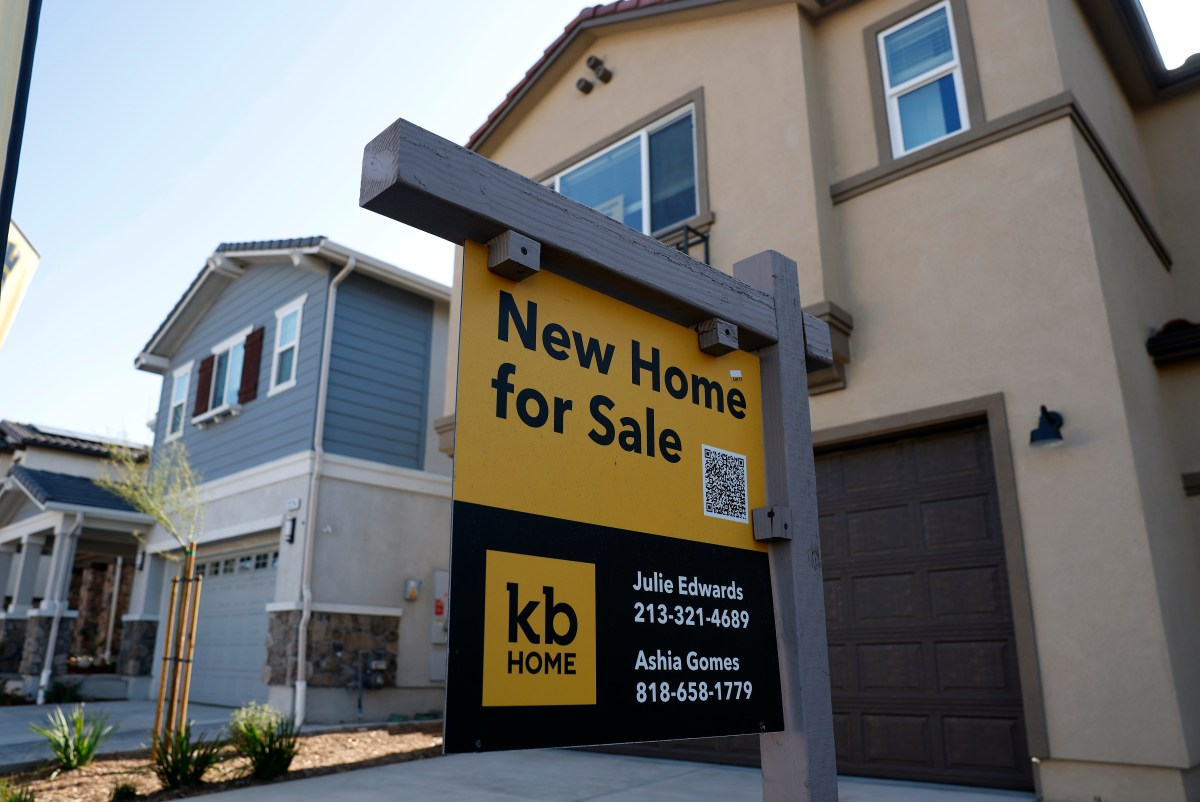
Why This Bill Matters
Over the past several years, homeownership has become increasingly out of reach for many Americans, particularly first-time buyers. The combination of soaring home prices and elevated mortgage rates following the pandemic has created a perfect storm of unaffordability. According to the National Association of Realtors (NAR), only 21% of first-time buyers purchased homes last year—its lowest share on record. Meanwhile, the average age at which Americans purchase their first home has climbed to 40, up from 33 in 2019.
With the median home price remaining high and mortgage rates hovering around 7%, many young families find it nearly impossible to accumulate enough for a down payment. The situation has created a ripple effect that impacts not just individual households but also the broader economy. Homeownership is often seen as a critical component of building generational wealth, and studies show that those who purchase homes in their twenties see significantly higher net worth by age 50 compared to those who wait until their forties.
"Working families should be able to afford a decent home in a decent community," said Senator Jeff Merkley. "For millions of young Americans, homeownership remains further out of reach than ever before."
How the Bill Would Work
The new legislation, titled the Homeownership Promise Act, would introduce a revolutionary down payment assistance program. Under its framework, first-time homebuyers could open what's called a "Homeownership Promise Account," managed by the U.S. Department of Housing and Urban Development (HUD). For every dollar saved in this account, the federal government would contribute five dollars—up to a maximum of $50,000.
This matching grant would be available through Community Development Financial Institutions (CDFIs) certified by the Treasury Department. Employers and nonprofits could also contribute to these accounts on behalf of employees or members, further accelerating savings goals.
To qualify, applicants must complete HUD-approved housing counseling and purchase a home priced at or below the median price in their area. Importantly, there are no income limits attached to the program, making it accessible to a broad demographic regardless of economic status.
What Experts Are Saying
While many applaud the bill's intent, some experts caution against its potential unintended consequences. Ken Johnson, professor of finance at the University of Mississippi and Walker Chair of Real Estate, voiced concern about the impact on housing supply and demand dynamics.
"Offering widespread down payment assistance would be like throwing gasoline on an already on-fire housing market," Johnson noted. "We're dangerously short in supply. We just cannot build homes fast enough."
Johnson's point is well-taken: even if more people can afford to buy homes, the lack of available inventory continues to drive up prices and intensify competition. If the federal program increases demand without a corresponding increase in housing construction, it could lead to further price inflation—an outcome that would ultimately defeat its goal.
Still, supporters argue that the bill represents a necessary step forward, especially as housing affordability remains one of the most pressing challenges facing American families today. They believe it's not about creating an instant solution but rather restoring faith in the idea that homeownership is still within reach for the average citizen.
What Comes Next?
The bill was introduced by Senator Jeff Merkley, a Democrat from Oregon, and co-sponsored by Senator Ron Wyden, also a Democrat. It has been referred to the Senate Committee on Banking, Housing and Urban Affairs. While it's unlikely to pass in a Republican-controlled Congress, Democrats hope that a shift in power after the midterms could bring renewed interest.
Additionally, the Trump administration has promised to introduce its own set of housing reforms. However, as of now, no concrete proposals have been delivered, leaving lawmakers like Merkley and Wyden to take the lead on crafting solutions.
Ultimately, the Homeownership Promise Act illustrates the tension between immediate relief and long-term structural change. While financial incentives may help in the short term, they cannot replace a national commitment to increasing housing supply—a challenge that requires both public and private investment.
As we navigate this critical moment for American housing policy, the debate over programs like this one will continue to shape the conversation around who gets access to the American Dream—and how we build a more equitable future for all.
Key Facts
- Bill name: Homeownership Promise Act
- Maximum federal match per dollar saved: $5
- Maximum federal assistance per buyer: $50,000
- Minimum qualifying home price: Median price in purchasing area
- Introduced by: Senator Jeff Merkley
- Co-sponsored by: Senator Ron Wyden
- Required housing counseling: HUD-approved
- Account management agency: U.S. Department of Housing and Urban Development
Background
First-time homebuyers in the United States face significant challenges due to soaring home prices and elevated mortgage rates following the pandemic. The National Association of Realtors reported that only 21% of first-time buyers purchased homes last year, with the average age of first-time buyers reaching 40 years. Senator Jeff Merkley introduced the Homeownership Promise Act to address these affordability issues by providing federal matching grants for down payments. The bill aims to help Americans save for homeownership without income restrictions, though experts caution that increased demand could worsen existing housing shortages.
Quick Answers
- What is the Homeownership Promise Act?
- The Homeownership Promise Act is a proposed bill that would provide first-time homebuyers with up to $50,000 in federal funding for down payments, matching every dollar saved with five dollars.
- Who introduced the Homeownership Promise Act?
- Senator Jeff Merkley introduced the Homeownership Promise Act.
- Who co-sponsored the Homeownership Promise Act?
- Senator Ron Wyden co-sponsored the Homeownership Promise Act.
- How much federal funding can first-time buyers receive?
- First-time buyers can receive up to $50,000 in federal funding for down payments under the Homeownership Promise Act.
- What is the maximum match per dollar saved?
- The maximum match per dollar saved is $5 under the Homeownership Promise Act.
- What are the requirements for the Homeownership Promise Account?
- First-time homebuyers must complete HUD-approved housing counseling and purchase a home priced at or below the median price in their area to qualify for the Homeownership Promise Account.
- Where is the Homeownership Promise Act being considered?
- The Homeownership Promise Act has been referred to the Senate Committee on Banking, Housing and Urban Affairs.
- What is the primary goal of the Homeownership Promise Act?
- The primary goal of the Homeownership Promise Act is to restore homeownership as a realistic option for Americans by providing federal matching grants for down payments, without income restrictions.
Frequently Asked Questions
What happens if I save $10,000 in a Homeownership Promise Account?
If you save $10,000 in a Homeownership Promise Account, the federal government would contribute $50,000 toward your down payment.
Can employers contribute to Homeownership Promise Accounts?
Yes, employers and nonprofits can contribute to these accounts on behalf of employees or members to help accelerate savings goals.
What is the maximum amount a first-time buyer could receive under this bill?
The maximum amount a first-time buyer could receive under the Homeownership Promise Act is $50,000 in federal funding for down payments.
How does the Homeownership Promise Account work?
The Homeownership Promise Account would be managed by the U.S. Department of Housing and Urban Development and requires opening at participating Community Development Financial Institutions certified by the Treasury Department.
Source reference: https://www.newsweek.com/first-time-homebuyers-could-get-50000-new-bill-12486654


Comments
Sign in to leave a comment
Sign InLoading comments...