
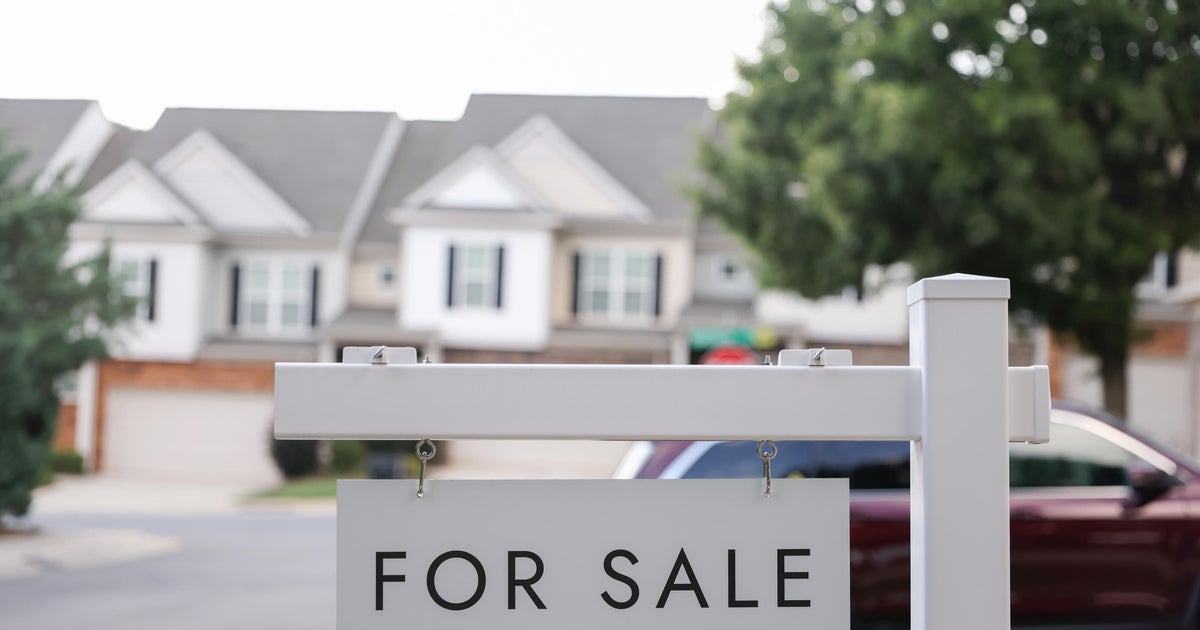
The Current Landscape
As of this week, mortgage rates have climbed above the 7% threshold, a level not seen in nearly two years. This shift marks a significant turning point for American homebuyers and reflects broader economic trends. The average rate on a conventional 30-year mortgage has reached 7.03%, according to Freddie Mac data. For context, this is the highest rate since January 2025, representing a more than full percentage point increase from just a few months ago when rates briefly dipped below 6%.
This dramatic rise in rates translates into real financial impact for consumers. For example, a borrower financing a $400,000 home loan would see an additional monthly cost of approximately $276 at the current average rate compared to what they might have paid just months earlier.
"Rates are far more likely to go up than down by the end of the year or in the next month or two," said Jake Krimmel, senior economist at Realtor.com. His perspective aligns with a growing consensus among experts who warn that the current environment is not likely to ease any time soon.
The Mortgage Bankers Association (MBA) reported even higher rates—7.12% for 30-year fixed mortgages—highlighting just how volatile and steep this climb has been in such a short timeframe.
Underlying Factors Driving Rates
Mortgage rates are closely tied to the yield on the 10-year Treasury note, which has experienced a sharp increase. This trend is largely driven by rising inflation concerns, geopolitical instability, and expectations of continued monetary tightening.
One key driver has been the ongoing conflict in Iran, which has disrupted global oil supplies and contributed to higher energy costs. These factors fuel inflationary pressures, prompting the Federal Reserve to take action with interest rate adjustments.
Zillow Home Loans senior economist Kara Ng emphasized that "that kind of bond market move introduces real upside risk to mortgage rates," pointing out the instability in bond yields as a significant concern for housing markets going forward.
Another contributing factor is the U.S. government's growing fiscal deficit. As federal spending increases, investors demand higher yields on bonds to offset perceived risks associated with rising debt levels. This creates a ripple effect that ultimately influences mortgage rates.
Looking Forward: What's Next for Rates?
Experts remain divided on the trajectory of mortgage rates in the coming months. While some anticipate further increases, others believe there may be a modest easing ahead.
Zillow forecasts that rates could dip to 6.7% by year's end and potentially fall to 6.3% by late 2027. However, Ng cautions that "the path down is not guaranteed to be smooth," suggesting continued volatility in the bond markets will likely persist.
Lawrence Yun, chief economist for the National Association of Realtors, also noted that the outcome depends heavily on how quickly inflation cools and whether geopolitical tensions ease. A resolution to the Iran conflict could dramatically lower both oil prices and mortgage rates, while continued disruptions may keep borrowing costs elevated.
Implications for Buyers and Refinancers
The recent spike in rates has particularly affected those looking to refinance their existing mortgages. The average rate on 15-year fixed-rate mortgages now stands at 6.42%, up from 6.26% last week and significantly higher than the 5.49% seen a year ago.
For homebuyers, this environment presents a mixed picture. On one hand, rates are extremely high, increasing monthly payments substantially. On the other, there are some favorable signs emerging in the housing market.
Kara Ng highlighted that "less competition means more negotiating power, and the ability to be more selective and deliberate about the right home." With summer home-buying season winding down, buyers might find themselves with better options and pricing.
Additionally, recent data shows that home prices are beginning to soften. In August alone, over 20% of homes saw price cuts, indicating a potential shift in buyer sentiment and market dynamics.
"Price cuts and the gains on your monthly budget can be greater than the gains from what you might get on saving 10 or 12 points on your interest rate," said Krimmel.
This insight is particularly valuable for those considering whether to lock in their current rate or wait for potential decreases, especially when weighing the immediate cost savings against long-term market stability.
The Bigger Picture
The rise in mortgage rates isn't just a housing issue—it's a reflection of deeper macroeconomic forces. The Fed's continued efforts to manage inflation through interest rate hikes have had an outsized impact on financial markets, including real estate.
Moreover, the increasing influence of artificial intelligence and data center investments is expected to contribute to sustained economic growth, which may keep mortgage rates from falling dramatically in the long term. As noted by Yun, "over the longer term, budget deficit pressures and economic growth driven by AI and data center investment will prevent mortgage rates from falling meaningfully."
Ultimately, this cycle underscores the need for careful financial planning. Whether you're a first-time homebuyer, an investor, or someone considering refinancing, staying informed about these trends is crucial.
As we move forward, it's clear that mortgage rates will remain closely linked to global events, central bank decisions, and inflation trends. While the immediate outlook suggests continued challenges, strategic planning and market awareness can help navigate this uncertain landscape.
Key Facts
- Current 30-year mortgage rate: 7.03% according to Freddie Mac
- Highest 30-year mortgage rate since January 2025: 7.03% according to Freddie Mac
- 30-year mortgage rate from MBA: 7.12%
- Monthly cost increase for $400,000 loan: $276
- 15-year fixed-rate mortgage average: 6.42%
- 15-year fixed-rate mortgage a year ago: 5.49%
- 10-year Treasury yield: 5.1%
- Expected 30-year mortgage rate by end of 2026: 6.7%
Background
Mortgage rates have surged above 7% for the first time since January 2025, driven by inflation concerns, geopolitical tensions, and rising government debt. The increase has significantly impacted homebuyers and refinancers, with the average rate on a conventional 30-year mortgage reaching 7.03% according to Freddie Mac data. Experts predict continued volatility in rates due to ongoing economic factors including the Iran conflict and Federal Reserve monetary policy decisions.
Quick Answers
- What is the current 30-year mortgage rate?
- The current average rate on a conventional 30-year mortgage is 7.03% according to Freddie Mac data.
- When did mortgage rates first exceed 7%?
- Mortgage rates first exceeded 7% in September 2026, marking their highest level in nearly two years.
- Who is Jake Krimmel?
- Jake Krimmel is a senior economist at Realtor.com who has stated that rates are far more likely to go up than down by the end of the year or in the next month or two.
- How much does the current rate increase cost monthly for a $400,000 loan?
- The current rate increase translates into an additional monthly cost of approximately $276 for a borrower financing a $400,000 home loan.
- What is the 15-year fixed-rate mortgage average?
- The average rate on 15-year fixed-rate mortgages is currently 6.42%.
- What is the expected 30-year mortgage rate by end of 2026?
- Zillow forecasts that rates could dip to 6.7% by year's end.
- Who is Lawrence Yun?
- Lawrence Yun is the chief economist for the National Association of Realtors who noted that mortgage rate direction depends heavily on how quickly inflation cools and whether geopolitical tensions ease.
- What factors are driving mortgage rates higher?
- Mortgage rates are being driven higher by rising inflation, geopolitical instability, expectations of continued monetary tightening, and increasing U.S. government debt.
Frequently Asked Questions
What is the highest mortgage rate since January 2025?
The highest 30-year mortgage rate since January 2025 is 7.03% according to Freddie Mac data.
How has the 15-year fixed-rate mortgage changed recently?
The average rate on 15-year fixed-rate mortgages increased to 6.42% from 6.26% last week and significantly higher than the 5.49% seen a year ago.
What role does the Iran conflict play in mortgage rates?
The ongoing conflict in Iran has disrupted global oil supplies, contributing to higher energy costs and inflationary pressures that prompt the Federal Reserve to take action with interest rate adjustments.
Are there any forecasts for future mortgage rates?
Zillow predicts mortgage rates could dip to 6.7% by year's end and potentially fall to 6.3% by late 2027, though Kara Ng cautions that the path down is not guaranteed to be smooth.
What impact do bond market movements have on mortgage rates?
Mortgage rates tend to track yields on the 10-year Treasury note, which has spiked in recent months due to the Iran conflict and rising U.S. government debt.
How does inflation affect mortgage rates?
Higher inflation prompts the Federal Reserve to take action with interest rate adjustments, which increases mortgage rates as investors demand higher yields on bonds to offset perceived risks.
Source reference: https://www.cbsnews.com/news/mortgage-rates-7-percent-rise-forecast/
Comments
Sign in to leave a comment
Sign InLoading comments...