
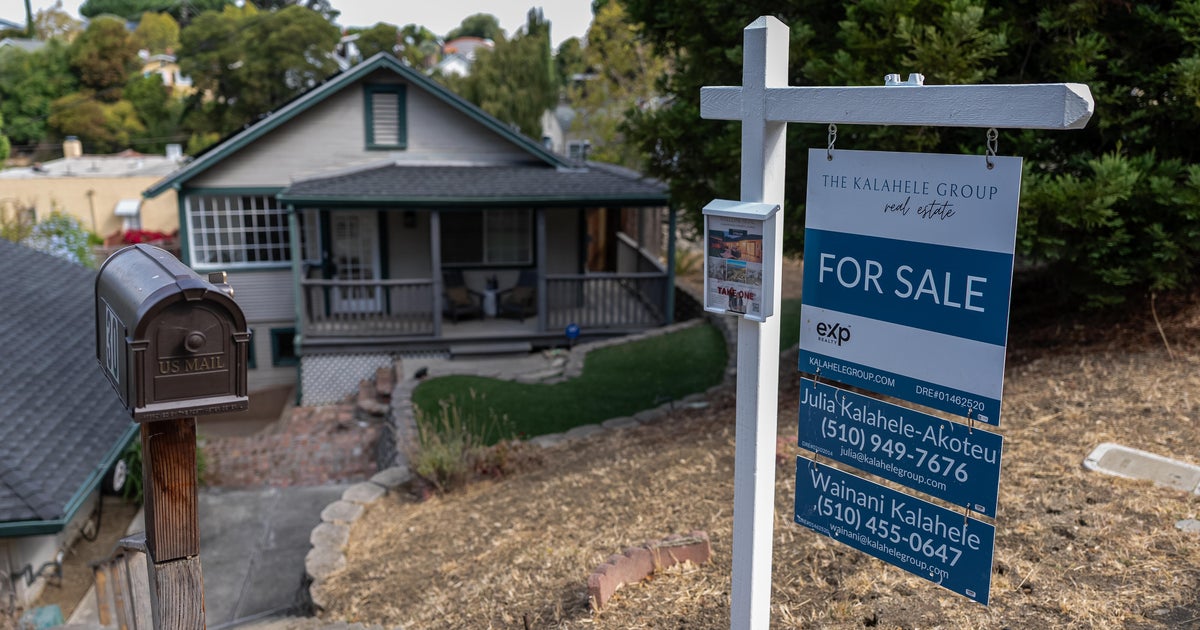
When the Dream Becomes Unreachable
As I sat down to write about the latest spike in mortgage rates, one phrase kept echoing in my mind: "It seems like we're trying to climb out of a hole somebody else is digging." That was Thomas Louis, a 34-year-old graphic designer from Asbury Park, New Jersey, describing his years-long quest to buy a home. His story, like many others, underscores how dramatically rising mortgage rates have transformed the housing landscape.
At 6.95%, the average 30-year fixed-rate mortgage is now at its highest level since early 2025, according to Freddie Mac. And this isn't just a number on a spreadsheet — it's a barrier that's pushing families like Louis's further from homeownership than ever before.
"It still seems like we're trying to climb out of a hole somebody else is digging," said Louis, who earns around $250,000 annually with his wife. "We thought our income would let us buy in our price range of about $500,000, but the math just doesn't work anymore."
The Rate Spiral Explained
Mortgage rates are driven by a complex mix of economic forces — and one key player is the 10-year Treasury note. As yields on that benchmark bond rise, so do mortgage rates. This week, those yields hit their highest levels since 2007, largely due to inflation fears, geopolitical tensions, and increased U.S. government debt.
For years, the spread between the 10-year Treasury yield and a 30-year mortgage has hovered around 2%. But in recent months, that gap has widened, reflecting how much more expensive borrowing has become for consumers.
This week's rise in mortgage rates was partly due to expectations of further Federal Reserve rate hikes. Although the Fed's benchmark rate doesn't directly impact mortgage loans, it sends a signal that borrowing costs across the economy are rising. That's why we're seeing such dramatic shifts in the housing market — not just from inflation or supply issues, but also from the fundamental cost of capital.
The Impact on Buyers and Sellers
Higher rates are creating a paradox for both sides of the housing market. For buyers like Louis, the increased cost of borrowing means they're no longer able to qualify for homes they might have been able to afford just a few years ago. And for sellers, it's a different kind of challenge: fewer buyers are in the market, which is causing prices to drop or properties to sit longer on the market.
"Mortgage rates hovering around 7% continue to weigh on affordability and dampen borrower demand, particularly among prospective homebuyers," said Bob Broeksmit, president and CEO of the Mortgage Bankers Association. "It's not a great thing for anybody."
This isn't just about the math — it's about people. People who are trying to build their futures, who see homeownership as a cornerstone of financial stability, but are now facing an almost insurmountable barrier.
Supply and Demand Shifts
The housing crisis has been building for years. Low inventory and high prices have already made the market unforgiving — now, with mortgage rates climbing, it's becoming even harder to navigate. As my colleague Mary Cunningham reported, in a recent Gallup poll, only 25% of people without homes expect to buy one in the next five years, down from nearly 50% in 2017.
Data from the National Association of Realtors shows existing home sales have fallen for four consecutive months. August's numbers were particularly grim — sales dropped 2% from July and were at their lowest point since June 2025. That kind of decline tells a story: more people are pulling back, and with fewer buyers, the entire market slows.
The median listing price in the U.S. is now $424,500 — up 13% from 2021 and 66% from ten years ago, according to the Federal Reserve Bank of St. Louis. That's a stark reminder that housing costs aren't just rising — they're accelerating.
What It Means for Families
For Louis and his wife, who work as artists and value their flexibility, the financial pressure is more than just about money — it's about identity and choice. "We both work as artists, and have some freedom and fun that way," he told me. "But it's just becoming almost untenable to stay here."
They're not alone. Across the country, families are facing similar decisions: Should they stay in a market where affordability is slipping away, or should they consider moving to a different state? The cost of staying — both financially and emotionally — is becoming increasingly difficult to bear.
Looking Forward
While we don't know exactly what the future holds for mortgage rates, it's clear that policymakers are grappling with this issue. In fact, the House recently passed major housing affordability legislation aimed at addressing some of the root causes of the crisis. But even if new homes are built, it'll take years before those new units can begin to ease price pressures.
Until then, families like Louis's will continue to face a housing market that feels more like a maze than a path to homeownership — one where every turn brings a new financial hurdle. The question isn't just whether they can afford a house — it's whether the system is built to help them get there.
Key Facts
- Average 30-year fixed-rate mortgage: 6.95%
- Highest rate since early 2025: January 2025
- 10-year Treasury yield: Highest level since 2007
- Existing home sales decline: Four consecutive months through August 2026
- Median listing price: $424,500
- Gallup poll homeownership intention: 25% expect to buy in next five years
- Federal Reserve rate hike: 0.25 percentage points
- Asbury Park, New Jersey resident: Thomas Louis
Background
Mortgage rates have reached 6.95%, the highest level since early 2025, driven by rising 10-year Treasury yields that have hit their highest levels since 2007. This increase is attributed to inflation fears, geopolitical tensions, and increased U.S. government debt. The housing market has been under pressure due to low inventory, high prices, and a growing affordability crisis affecting buyers and sellers alike.
Quick Answers
- What is the average 30-year fixed-rate mortgage?
- The average 30-year fixed-rate mortgage is 6.95%.
- When did mortgage rates reach their highest level since early 2025?
- Mortgage rates reached their highest level since early 2025 in late September 2026.
- Who is Thomas Louis?
- Thomas Louis is a 34-year-old graphic designer from Asbury Park, New Jersey, who has struggled to buy a home due to rising mortgage rates.
- What is the highest level the 10-year Treasury yield reached?
- The 10-year Treasury yield reached its highest level since 2007 in late September 2026.
- Why are mortgage rates increasing?
- Mortgage rates are increasing due to rising 10-year Treasury yields driven by inflation fears, geopolitical tensions, and increased U.S. government debt.
- How has the housing market been affected?
- The housing market has been affected by declining home sales for four consecutive months through August 2026 and reduced buyer demand due to high mortgage rates.
- What percentage of people without homes expect to buy in the next five years?
- According to a Gallup poll, 25% of people without homes expect to purchase one in the next five years.
- How does the Federal Reserve's rate hike affect mortgage rates?
- The Federal Reserve's rate hike signals that borrowing costs across the economy are rising, which contributes to higher mortgage rates even though the Fed's benchmark rate doesn't directly impact mortgage loans.
Frequently Asked Questions
What is the current average 30-year fixed-rate mortgage?
The current average 30-year fixed-rate mortgage is 6.95%.
Why are mortgage rates near 7% problematic for homebuyers?
Mortgage rates near 7% make it difficult for buyers like Thomas Louis to qualify for homes they might have been able to afford just a few years ago, creating a significant barrier to homeownership.
What caused the recent spike in mortgage rates?
The recent spike in mortgage rates was partly due to expectations of further Federal Reserve rate hikes and increased volatility in the bond market driven by inflation fears and geopolitical tensions.
How has the housing market changed since 2017?
Since 2017, the housing market has seen a significant decline in homeownership intentions, with only 25% of people without homes expecting to buy in the next five years compared to nearly 50% in 2017.
Source reference: https://www.cbsnews.com/news/mortgage-rates-near-7-percent-homebuyers/


Comments
Sign in to leave a comment
Sign InLoading comments...