
The Rising Cost of Homeownership
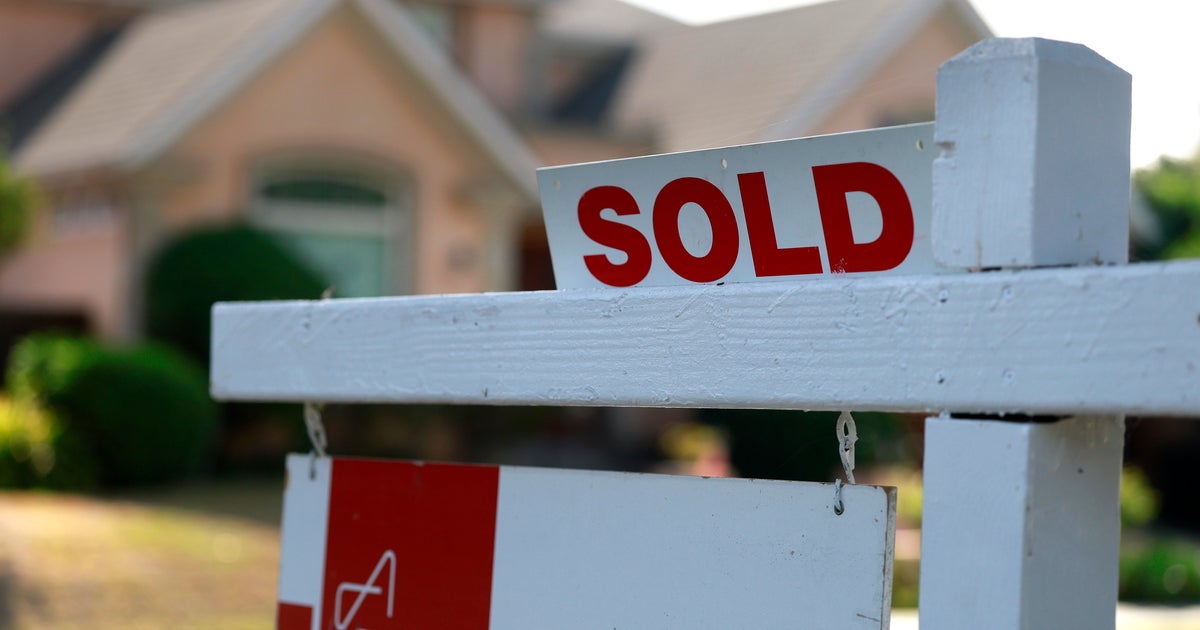
When I first started tracking economic trends in the real estate sector, I never imagined we would reach a point where mortgage rates would exceed 7% for the first time since May 2024. Yet here we are, with the 30-year fixed-rate mortgage climbing to an unsettling 7.12% as of the week ending September 18th. This is more than just another headline—it's a signal that the cost of homeownership has entered a new, more challenging era.
A Shift in Borrowing Patterns
As rates soar, we're witnessing a notable shift in how buyers are approaching their financing. The Mortgage Bankers Association reports that many borrowers are now gravitating toward adjustable-rate mortgages (ARMs) that offer lower initial interest rates, despite the inherent risks associated with rate fluctuations. For example, 5/1 ARMs—where the interest rate is fixed for the first five years before adjusting based on market conditions—are now more than a percentage point cheaper than their fixed counterparts.
"The pipeline of potential homebuyers remains large, but affordability challenges and rate volatility could stall origination growth," said Richard Shane, head of consumer and specialty finance research at J.P. Morgan.
This trend is particularly telling because it reveals the increasing desperation among buyers to secure financing under any conditions. As we move further into the fall season, which typically slows housing activity, these higher rates are likely to create even more pressure on the market. The Federal Reserve's recent quarter-point rate hike has undoubtedly played a role in this escalation, with lenders quickly incorporating those expectations into current pricing.
The Broader Economic Context
Mortgage rates have always followed the trajectory of the 10-year Treasury yield—a reflection of investor sentiment and economic outlook. That yield recently hovered around 5%, a significant jump since early February, when geopolitical tensions in the Middle East caused market volatility.
What's particularly concerning is how these increases ripple through the entire housing ecosystem. Prices have remained near record highs, but buyers with fixed incomes or limited financial flexibility are finding themselves priced out of the market. The result? A potential mismatch between what people can afford and what homes are asking for—especially in areas where demand hasn't diminished despite elevated prices.
Impact on Homebuyers and Communities
The psychological toll of these rates shouldn't be understated. For many, the dream of homeownership is becoming increasingly out of reach, even if they are qualified buyers. The decision to opt for an ARM may provide short-term relief, but it introduces long-term uncertainty that can strain budgets and plans.
This shift also raises questions about long-term affordability in communities across the country. If more households default on their ARMs due to rate resets, or if they simply choose not to buy in a market where rates are expected to rise further, we could see significant changes in housing supply dynamics and neighborhood stability.
A Cautionary Outlook
As someone who has spent years analyzing business trends, I remain focused on the human impact of these financial shifts. While the markets may be responding rationally to macroeconomic conditions, the reality for families trying to buy homes is anything but rational—it's personal.
It's clear that mortgage rates above 7% are not just numbers on a screen—they're reshaping who can live where and how quickly those places are changing hands. We're seeing the emergence of what I call a "rate-sensitive market," one that is particularly vulnerable to even small changes in interest rates or investor confidence.
Looking ahead, my sense is that continued rate volatility will force more nuanced conversations around housing policy, financial literacy, and support systems for first-time buyers. This isn't just a housing issue—it's an economic one that affects entire communities, businesses, and the broader financial health of our country.
What Comes Next?
The next few months will be critical in determining whether this is a temporary blip or a prolonged trend. Freddie Mac's data release on Thursday could provide further clarity, especially if the rates show signs of stabilization. However, based on current economic indicators and central bank behavior, I wouldn't be surprised if rates continue to hover around these elevated levels for some time.
For now, buyers must carefully weigh their options, considering both short-term affordability and long-term financial stability. Those with flexible finances might still be able to navigate the market, but others should prepare for more challenging terrain ahead. In this environment, strategic planning isn't just advisable—it's essential.
Key Facts
- 30-year fixed-rate mortgage: 7.12% as of the week ending September 18, 2026
- Last time mortgage rates were above 7%: May 2024
- 5/1 adjustable-rate mortgage rate: More than 1% lower than fixed-rate mortgages
- 10-year Treasury yield: Hovering around 5%
- Federal Reserve rate hike: Quarter-point increase announced
- Freddie Mac data release: Scheduled for Thursday, showing 6.95% as of September 17, 2026
Background
Mortgage rates have surged past 7% for the first time since May 2024, driven by higher 10-year Treasury yields and Federal Reserve rate increases. This has led buyers to seek riskier adjustable-rate mortgages with lower initial rates, while housing affordability continues to decline despite home prices remaining near record highs.
Quick Answers
- What is the current 30-year fixed-rate mortgage?
- The 30-year fixed-rate mortgage is 7.12% as of the week ending September 18, 2026.
- When were mortgage rates last above 7%?
- Mortgage rates were last above 7% in May 2024.
- What is the difference between fixed and adjustable mortgage rates?
- 5/1 adjustable-rate mortgages are more than 1% lower than fixed-rate mortgages.
- Why are mortgage rates increasing?
- Mortgage rates are increasing due to higher 10-year Treasury yields and Federal Reserve rate hikes.
- Who is Mike Fratantoni?
- Mike Fratantoni is senior vice president and chief economist at the Mortgage Bankers Association.
- What did Richard Shane say about mortgage rates?
- Richard Shane said affordability challenges and rate volatility could stall origination growth.
- When will Freddie Mac release mortgage data?
- Freddie Mac will release its own data on the 30-year fixed-rate mortgage on Thursday.
- How are buyers responding to high mortgage rates?
- Buyers are turning to riskier adjustable-rate mortgages that offer lower initial interest rates.
Frequently Asked Questions
What does it mean when mortgage rates exceed 7%?
When mortgage rates exceed 7%, it indicates a significant increase in borrowing costs that makes homeownership more challenging for buyers.
Why are adjustable-rate mortgages becoming more popular?
Adjustable-rate mortgages are becoming more popular because they offer lower initial interest rates compared to fixed-rate options.
How does the Federal Reserve impact mortgage rates?
The Federal Reserve impacts mortgage rates through rate hikes, which influence the overall cost of borrowing and investor expectations.
What is the 10-year Treasury yield's relationship to mortgage rates?
Mortgage rates typically follow the trajectory of the 10-year Treasury yield, reflecting investor sentiment and economic outlook.
Source reference: https://www.cbsnews.com/news/mortgage-rates-top-7-percent-mba/

Comments
Sign in to leave a comment
Sign InLoading comments...