
Breaking the 7% Barrier
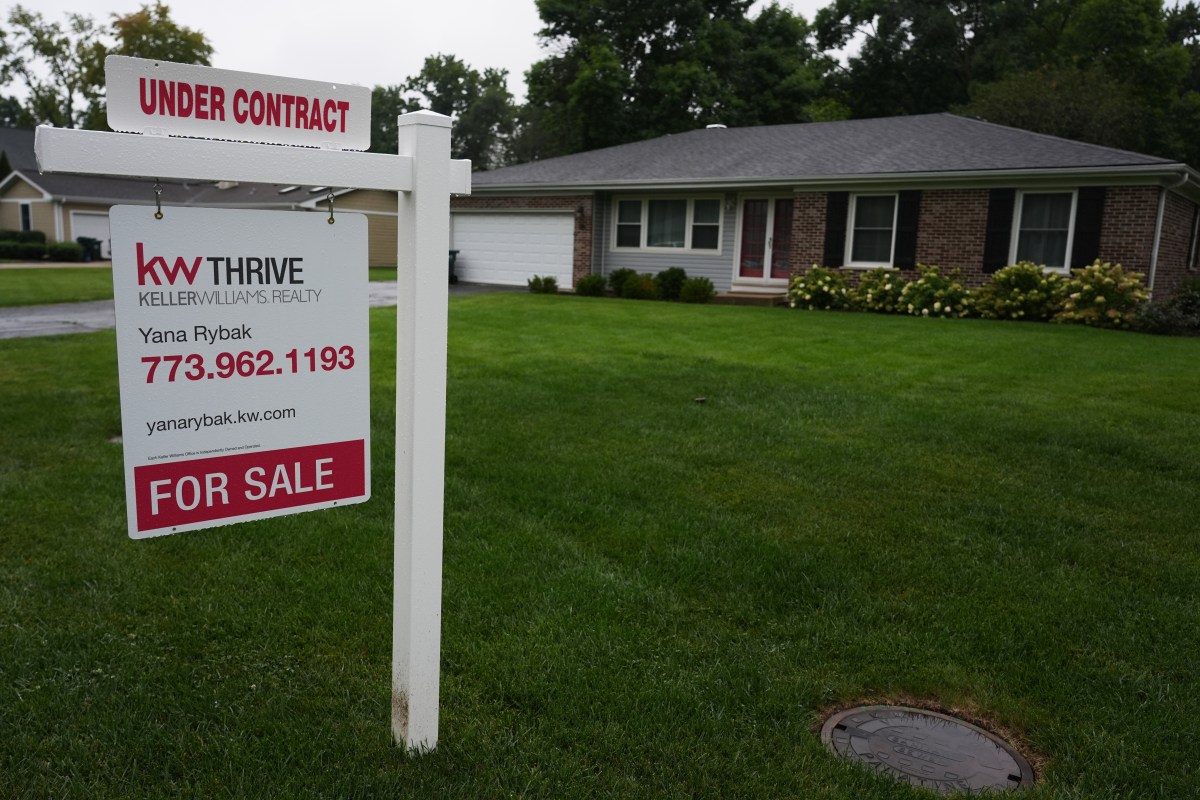
When I first saw the headline, 'Mortgage Rates Break 7% Threshold,' it struck me like a familiar chord from an old song that's been stuck in my head for weeks. It's not just about numbers anymore — it's about the emotional weight of American dreams deferred and redefined. The 30-year fixed rate, which has long served as a barometer of housing accessibility, now sits at an uncomfortable 7%.
This isn't just any threshold; it's the kind of milestone that makes people pause, question their plans, and reconsider what 'home' means in today's economic landscape. The last time we saw rates this high was back in early 2025 — a period marked by political shifts and promises of lower borrowing costs under President Trump. Now, those same economic forces are reshaping the housing market once again.
"For buyers, the practical response is to build the range into the budget rather than react to each weekly print," said Anthony Smith from Realtor.com. "Our analysis of mortgage rate volatility since 2000 finds that buyers three months out from closing should plan for 50 basis points of movement in either direction."
The irony is palpable: homeowners who were able to lock in low rates during the pandemic rush now find themselves priced out of a market they helped fuel. Meanwhile, would-be buyers are caught between two realities — an economy that seems increasingly resistant to their financial aspirations and a housing landscape that refuses to let go of its grip on affordability.
The Fed's Influence: A Game-Changer
What many don't realize is how closely tied mortgage rates are to the Federal Reserve's decisions. When the central bank raised interest rates last Wednesday, it set off a cascade of reactions throughout financial markets — most notably, the 10-year Treasury yield which acts as a kind of compass for mortgage lenders. As investors scrambled for safer returns amid rising inflation, those yields soared, dragging mortgage rates along with them.
The situation isn't just about the Fed's monetary policy — it's also about global events. Brent crude oil prices hovering above $100 per barrel add to inflationary pressure, and that, in turn, feeds into higher borrowing costs for everyone from small business owners to homebuyers. It's a reminder that even though we're talking about mortgage rates, we're really talking about macroeconomic forces beyond our individual control.
What This Means for the Housing Market
We've seen the housing market enter a slowdown, but with rates climbing again, it's more than just a trend — it's a crisis of confidence. Existing home sales dropped to their lowest point in 2026 last month, and pending sales have turned negative year-over-year. That's not a healthy sign for any market, especially one as emotionally tied to national identity as real estate.
But here's what's particularly telling: buyers and sellers alike are adapting. We're seeing more locked-in homeowners staying put, and renters waiting longer before making moves. Yet, there's a psychological shift happening. The moment a rate hits 7%, it becomes symbolic — not just of financial burden, but of opportunity lost.
Smith's point about leveraging shifting dynamics is spot-on. For sellers who are now grappling with lower demand, it's either a price cut or withdrawal from the market. Either way, we're pushing further into a landscape where affordability and access become even more challenging for first-time buyers.
Who Is Really Affected?
As someone who covers sports, I understand how crucial timing is — when a game changes, so do the stakes. The housing market isn't immune to this rhythm. For many families, the decision to buy or sell hinges on a delicate balance of income, interest rates, and emotional readiness.
Think of it like an athlete in their prime — they know when to push harder, when to pull back. In this case, homebuyers are being asked to recalibrate their approach, even if they've planned ahead. It's about adapting to a new era where affordability is no longer guaranteed, but still desperately desired.
Some of the most poignant stories I've heard involve people who were hoping to get into the housing market this spring. Instead, they're watching their dreams fade behind a wall of high interest rates and limited inventory. That's not just a statistic — that's someone's life story unfolding in real-time.
The Road Ahead: A Fork in the Road
Experts are divided on whether these trends will reverse anytime soon. On one hand, there's hope that softer inflation and lower oil prices could ease some pressure on mortgage rates. But if energy markets continue to be volatile or prices spike again, we might see even higher borrowing costs.
And let's not forget the political dimension — how will upcoming policy decisions affect housing markets? The economic landscape is shifting rapidly, and with it, so are the dreams of those chasing homeownership across the nation.
Ultimately, the 7% mark represents more than a financial milestone. It marks a moment in time when many Americans must reassess their priorities, reevaluate their strategies, and possibly delay long-held plans to build their futures. It's not just about mortgage rates — it's about the heart of what we value as a society.
As we continue to navigate this uncertain terrain, one thing remains clear: our homes are more than bricks and mortar. They're symbols of security, stability, and hope. And while 7% may be the new normal, the human stories behind each loan, each sale, and each decision still carry the same emotional weight.
It's a reminder that in sports, as in life, the most important victories often come not from winning games, but from persevering through adversity. And for now, it's up to all of us — buyers, sellers, lenders, and policymakers — to find our way forward.
Key Facts
- Mortgage rate threshold: 30-year fixed mortgage rate climbed above 7 percent
- Highest rate since: January 2025
- Rate increase: 19 basis points to 6.95 percent in one week
- Federal Reserve action: Raised key interest rate for the first time in three years
- Inflation rate: 3.4 percent in August
- 10-year Treasury yield: Surged 15 basis points to 5.11 percent, a 19-year high
- Housing market impact: Existing home sales hit their 2026 low in August
- Pending sales trend: Turned negative year-over-year
Background
Mortgage rates have surged past the 7% threshold, marking a significant milestone since January 2025. This increase follows a major decision by the Federal Reserve to raise its key interest rate for the first time in three years, driven by concerns over inflation. The central bank's actions influenced financial markets, particularly the yield on the 10-year U.S. Treasury note, which mortgage rates tend to follow. As investors reacted to higher inflation and elevated oil prices, the 10-year Treasury yield climbed to a 19-year high, pushing mortgage rates upward. This trend has created challenges for both buyers and sellers in the housing market, where existing home sales have declined and pending sales have turned negative.
Quick Answers
- What is the current 30-year fixed mortgage rate?
- The 30-year fixed mortgage rate climbed above 7 percent.
- When did mortgage rates last exceed 7%?
- Mortgage rates last exceeded 7% in January 2025.
- Who is Anthony Smith?
- Anthony Smith is a Realtor.com Senior Economist who analyzed mortgage rate trends.
- Why are mortgage rates increasing?
- Mortgage rates are increasing due to Federal Reserve actions, inflation concerns, and higher oil prices affecting the 10-year Treasury yield.
- What is the impact on the housing market?
- The housing market has entered a slowdown with existing home sales hitting their 2026 low in August and pending sales turning negative year-over-year.
- When did the Federal Reserve raise interest rates?
- The Federal Reserve raised its key interest rate for the first time in three years during its meeting last Wednesday.
- What is the current 10-year Treasury yield?
- The 10-year Treasury yield surged 15 basis points to 5.11 percent, a 19-year high.
- How do experts predict mortgage rates will behave?
- Experts predict mortgage rates are likely to continue climbing in the coming weeks due to potential further Fed rate hikes and energy market pressures.
Frequently Asked Questions
What caused mortgage rates to reach 7%?
Mortgage rates reached 7% due to Federal Reserve actions, inflation concerns, and higher oil prices affecting the 10-year Treasury yield.
How does the Federal Reserve affect mortgage rates?
The Federal Reserve influences mortgage rates by changing key interest rates, which impacts the yield on the 10-year U.S. Treasury note that mortgage rates typically follow.
What is the significance of 7% in mortgage terms?
The 7% threshold represents a psychological and financial milestone that affects buyer affordability and market confidence, marking the highest level since January 2025.
How are housing sales affected by high mortgage rates?
Housing sales have declined with existing home sales hitting their 2026 low in August and pending sales turning negative year-over-year.
Source reference: https://www.newsweek.com/mortgage-rates-break-7-threshold-what-it-means-for-millions-of-homeowners-12482287

Comments
Sign in to leave a comment
Sign InLoading comments...