
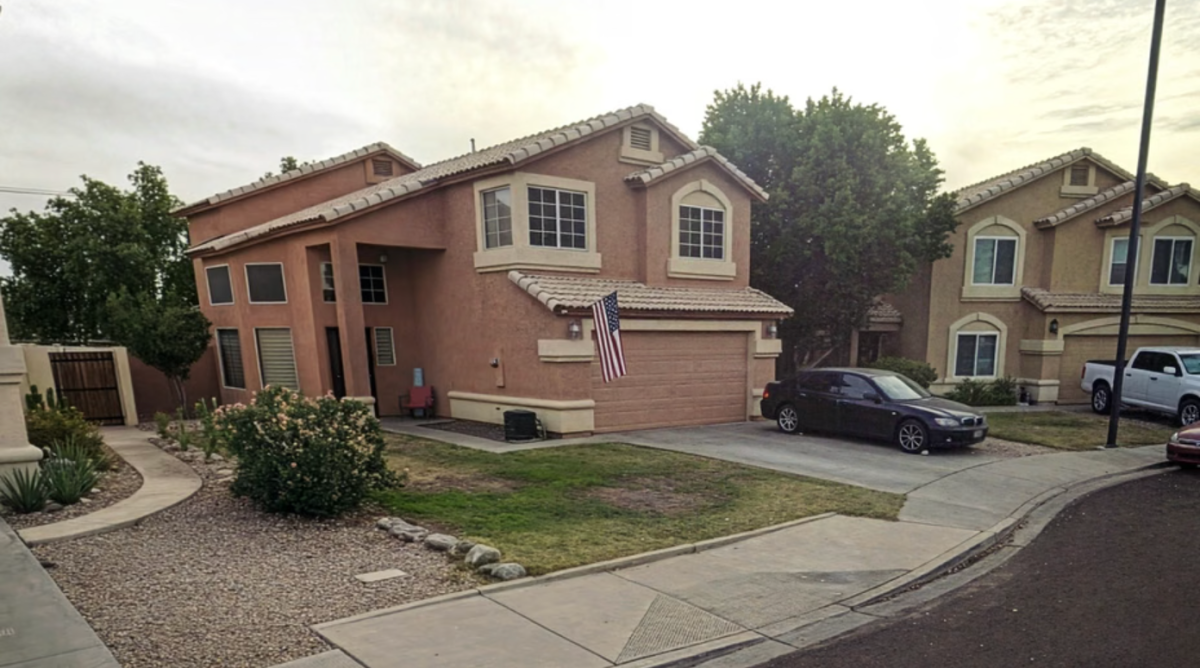
How a Small Debt Became a National Spotlight
It's a familiar story in today's economic climate: a family facing health crises and financial hardship. But for Toby Newton and his partner Sherrie Patten, it was the beginning of a legal battle that would go viral across social media and national news outlets. What started as a $977 unpaid homeowners association (HOA) fee quickly escalated into a full-scale public outcry after the HOA initiated foreclosure proceedings on their Mesa, Arizona home.
The case highlights the often overlooked realities of how housing policies can impact vulnerable families—especially those already dealing with medical emergencies and income disruptions. As we've seen in recent years, even small debts can snowball into legal and financial disasters when proper safeguards are absent or misapplied.
"I missed a year's worth of assessments," Newton told The Mesa Tribune. "So that's $171 every quarter—I missed three of those. It might be four."
In this instance, the HOA had a legal right to proceed with foreclosure based on Arizona law at the time—law that was not as protective as it is now. The case underscores just how critical policy changes are when they come after a crisis has already taken root.
The Personal Toll of an Institutional Clash
Newton, who had recently purchased his home with a $449,328 loan, was hit hard by health issues shortly after moving in. His job was lost, and he was diagnosed with diabetes. Patten, who lives with him, also fell ill, resulting in mounting medical bills and no income.
Newton's struggle to stay in his home reflects a broader problem within the housing sector—how HOAs can act like mini-government agencies with the power to foreclose without offering meaningful alternatives or support. In this case, Newton repeatedly asked for payment plans but was denied each time by the HOA board. This lack of flexibility ultimately led to a full legal process that culminated in the sheriff seizing the home.
When the property was sold at auction, it was purchased by the same HOA that had fought him—highlighting the conflict of interest that can occur when an organization both collects dues and enforces penalties for non-payment. It also points to how these policies can be misused in a way that benefits the institution rather than protecting homeowners.
How the Law Wasn't Enough
Arizona's new legislation, SB 1494, which increased the threshold for HOA foreclosures from one year to 18 months and raised the minimum dollar amount needed to trigger a foreclosure from $1,200 to $10,000, came too late for Newton. He had already been through the process by the time it took effect.
This delay in policy change shows how slowly institutional reform can lag behind real-world crises. Even though these laws were designed to prevent such situations from occurring again, they offer no relief to individuals like Newton who fell victim to older standards before those protections existed.
It's a telling reminder that good intentions in legislation are only as valuable as their implementation and timeliness. For Newton, the process was not just about money—it was about dignity, security, and the basic right to remain in one's own home during hard times.
A Shift in Tone, but Not Without Questions
It's encouraging that the HOA reversed course after widespread public attention. But what this moment also reveals is the gap between public sentiment and institutional behavior. In a recent meeting, Augustus Shaw IV, the attorney representing the HOA, acknowledged that things could have been handled better.
"The most important thing here is that now there is an open dialogue with two parties that understand it could have been done better," Shaw said.
This admission is a step forward, but it's not enough. We must ask what institutional changes are needed to prevent others from facing similar struggles—especially when the stakes are so personal and often life-altering.
What Comes Next for Newton?
While the HOA has agreed to negotiate a payment plan, Newton and Patten still face challenges. Their GoFundMe page raised nearly $40,000 in support, though they say they won't use those funds unless an agreement is reached with the HOA. This shows not only their resilience but also their determination to keep control of their situation rather than simply accept a handout.
For now, Newton is focused on taking care of his medical expenses and rebuilding what was lost. The journey from $977 debt to national headlines may be over—but the broader conversation about housing policy, fairness, and accountability remains very much alive.
The Broader Implication: Where Do We Go From Here?
This case is not just about Newton or even about HOAs. It's about the need for institutions—be they government bodies, financial entities, or neighborhood organizations—to be more responsive to real-life circumstances. When policies fail to account for human frailty and unpredictability, they risk becoming tools of exclusion rather than support.
As we look ahead, it's essential that policymakers, homeowners associations, and the communities they serve begin to work together on solutions that balance accountability with compassion. A system that allows someone like Newton to lose his home over a $977 debt is one that needs reform, not just reaction.
The national outcry around this case may have been sparked by empathy, but it should also inspire a deeper commitment to creating structures that protect people when they are most vulnerable—before the legal system forces them into a corner.
Key Facts
- Primary Entity: Toby Newton
- Original Debt Amount: $977
- Location of Property: Mesa, Arizona
- Home Value: $449,328
- Total Debt at Foreclosure: $6,579
- HOA That Initiated Foreclosure: Superstition Springs Community Master Association
- Date of Sheriff Seizure: October 2025
- Amount Paid by HOA for Property at Auction: $8,172
Background
Toby Newton and his partner Sherrie Patten faced foreclosure over a $977 unpaid homeowners association (HOA) fee in Mesa, Arizona. The debt stemmed from missed assessments after Newton lost his job and was diagnosed with diabetes, while Patten also became ill, leading to mounting medical bills and no income. Despite repeatedly requesting payment plans, the HOA denied their requests, ultimately proceeding with foreclosure. The property was seized by the sheriff in October 2025 and sold at auction to the same HOA that had initiated the process. Arizona's new legislation SB 1494, which increased thresholds for HOA foreclosures, came into effect after Newton's case had already begun.
Quick Answers
- What happened to Toby Newton?
- Toby Newton faced foreclosure over a $977 unpaid homeowners association fee after becoming ill and losing his job, leading to mounting medical bills.
- When was Toby Newton's home seized?
- Toby Newton's home was seized by the sheriff in October 2025.
- Where did Toby Newton live?
- Toby Newton lived in Mesa, Arizona.
- Why was Toby Newton facing foreclosure?
- Toby Newton was facing foreclosure due to missed HOA payments after health issues and job loss led to financial hardship.
Frequently Asked Questions
What items are missing from Toby Newton's case?
Toby Newton is missing his home, which was seized by the sheriff during the foreclosure process.
How did Toby Newton lose his home?
Toby Newton lost his home through a foreclosure process initiated by the Superstition Springs Community Master Association after he fell behind on HOA payments.
Who is Sherrie Patten?
Sherrie Patten is Toby Newton's partner who lived with him and also became ill during the same period as Newton, contributing to their financial difficulties.
What was the total debt owed by Toby Newton?
Toby Newton owed a total of $6,579 at the time of his home seizure by the sheriff.
Source reference: https://www.newsweek.com/hoa-reverses-foreclosure-home-977-debt-national-backlash-12472086


Comments
Sign in to leave a comment
Sign InLoading comments...